A payment and banking strategy decides how money enters a company, who holds it, what each flow costs and which payment methods each market needs, before the product is built. For the merchants of PSPs, PayFacs, ISOs and ISVs, it is largely the strategy their platform builds in, which NORBr's white-label payment infrastructure makes configurable per merchant.
Most companies build a minimum viable product first and look for a bank and a payment provider afterwards. Viktoria Soltesz, Founder of the Soltesz Institute, argues for the opposite order. In Season 7 of NORBr's #TheShot, she explains why money flows have to be planned first, and why the decisions around them need an owner who is not only the finance team.
Her audience is founders and operators. Her questions are the same ones PSPs, PayFacs, ISOs and ISVs answer every day on behalf of their merchants: who holds the funds, what a flow really costs, what happens when a provider pulls the plug. This article, updated in October 2026, follows the five episodes of Season 7 and adds the market data behind them.
Key takeaways on payment and banking strategy:
- Every movement of money triggers risk and fees, and touches security, user experience, finance and technology at once.
- Payment fees are charged on revenue, taxes on profit, so payment costs can weigh more on margin than taxes.
- Finance teams are not trained to choose between SEPA, open banking, QR codes or wallets, which is why Viktoria makes the case for a chief payment officer.
- Orchestration is a necessary tool for multi-market companies, but it does not replace the strategy that decides how to use it.
Why should money flows be planned before the product?
Because the product depends on what the company is allowed to do with money in each market. Which services can be sold in one country but not in another, which banks will accept the business, what the risk around each rail is: those answers shape pricing, onboarding, KYC flows and customer service.
"Companies are coming up with a minimum viable product. They are rushing, they are creating the service or product at a bare minimum level, and then they try to find a bank and payment provider after that. What we are advocating for is the complete opposite. You need to understand how the money is flowing through your organization, what you are allowed to do, and then build the operation around that." Viktoria Soltesz, Founder, Soltesz Institute, in Episode 1
The order matters most for startups. In Episode 4, Viktoria explains why high street banks reject them: little volume, changing activities, no track record. Under investor pressure, some companies then onboard with providers nobody has heard of. She describes a client whose funds got stuck with such a provider, part of them lost, and the rest returned as a paper cheque the founder had to fly abroad to collect.
How can payment fees cost more than taxes?
Payment fees are charged on revenue. Taxes are charged on profit. On a thin margin, that difference changes everything.
Viktoria's example in Episode 2 runs as follows. A company sells a product for €100 that costs €80 to make, for a €20 profit. Corporate tax takes a share of the €20. Card fees, fixed fees and the rest of the provider's charges can reach €5 on the €100, which is a quarter of the profit before tax is even calculated. A company that spends months optimizing its tax structure and minutes choosing its payment provider has the priorities upside down.
Regulation caps only part of that cost. In the EU, the Interchange Fee Regulation limits interchange to 0.2% of the transaction value for consumer debit cards and 0.3% for consumer credit cards. Scheme fees and the acquirer's margin sit outside those caps, and the European Commission's report on the application of the regulation found that scheme fees had increased, to a limited extent, after the caps came in. NORBr's guide to payment processing fees breaks down each layer.
Who should own payment and banking decisions?
Not the finance team alone. Viktoria, who trained in accounting herself, is direct about it: accountants learn debits, credits, tax and budgeting, not SEPA, ACH, open banking, QR codes or crypto, and not user experience or data security.
"If your accountant is making a decision on user experience or technology, you are in trouble." Viktoria Soltesz, in Episode 3
Her answer is a chief payment officer, a role she develops in her book The CPayO: one senior person who oversees money from the moment it enters the company to the moment it leaves as payroll, supplier payments or dividends, with enough knowledge of compliance, risk, technology and user experience to decide across all of them. In large companies, the role forces someone to take responsibility for decisions that otherwise fall between the head of legal, the CFO and a product manager.
What happens when a market does not pay by card?
The marketing works and the checkout fails. Viktoria's example is a company that launches in a new country with its existing card-only provider, where most people pay with open banking, QR codes, bank transfers or cash. Visitors arrive, click, try to pay, and cannot.
The data supports the warning. According to the Global Payments Report 2026 published by Global Payments, digital wallets accounted for 56% of global e-commerce value in 2025, and in China, Alipay and WeChat Pay alone represented 89% of e-commerce value. A card-first checkout leaves most of that spending unaddressed. NORBr's article on QR code payments in Asia and the #PayWorldTour guides map these preferences country by country.
Is payment orchestration enough to run payments across markets?
It is necessary, and it is not enough. In Episode 5, Viktoria calls orchestration and omnichannel tooling "the bare minimum basis" of a payment strategy for an international business. The tools connect several providers, route volume between them, provide backups and consolidate reports for reconciliation.
What they do not do is decide. A provider offers volume discounts to win more of a company's traffic, which also concentrates the risk on that provider. How much volume to keep with it, which backup to activate in each market, when to accept a higher fee for a lower risk: those are strategy decisions that a person has to make, then encode in the tools.
What does this mean for PSPs, PayFacs and ISVs?
The merchants of a PSP, a PayFac or an ISV rarely have a chief payment officer. Their payment strategy is, in practice, the one their operator builds into the platform: which acquirers they can reach, which local payment methods are available in each country, how transparent the fees are, and what happens when one provider goes down.
On NORBr's white-label payment infrastructure, an operator connects several acquirers and local payment methods through one payment network, sets routing rules for cost, approval and backup, and gives its merchants the fee and performance data from the analytics dashboards under its own brand. Onboarding a merchant on more than one acquirer is covered in multi-acquirer merchant onboarding. The infrastructure makes the decisions executable. The operator, and its merchants, still make them.
Who is Viktoria Soltesz?
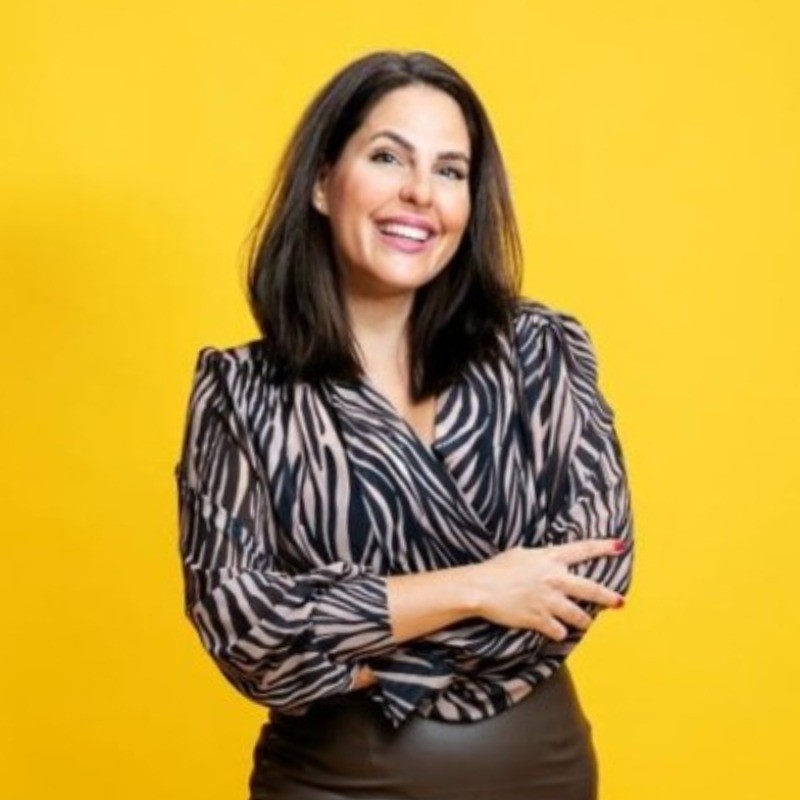
Viktoria Soltesz, Founder, Soltesz Institute. Viktoria has spent more than 20 years in payments and finance, starting in accounting software and finance before founding the payment and banking consultancy PSP Angels. Through the Soltesz Institute, she offers EU-accredited training and certification in payments and banking. She is the author of Moving Money: How Banks Think and The CPayO, on the role of the chief payment officer. Follow her on LinkedIn and the Soltesz Institute on LinkedIn.
A company that optimizes its taxes and improvises its payments is optimizing the smaller of its two bills.
NORBr is the white-label payment infrastructure for PayFacs, PSPs, ISOs and ISVs. Operators connect acquirers and local payment methods once, then give each merchant the routing, backup and reporting its markets require.
About #TheShot: a video series sharing clear, unsponsored insights from payment professionals. One expert, one topic, short episodes. Watch Season 7 with Viktoria Soltesz or browse all seasons.